Why credit AI regulation matters now — scope and promise of this guide
Using clever computer programs, or artificial intelligence (AI), to make decisions about giving out credit is becoming very popular. It helps banks and lenders work faster and often make better choices. But here’s the thing: these new "ai applications" are growing so quickly that the rules about them, called regulations, are struggling to keep up. In 2026, this difference between fast AI growth and slow rule-making is a big challenge for many businesses.
Across the world, different countries are trying to figure out the best way to manage this. For example, parts of the EU AI Act that deal with high-risk areas like checking someone’s credit score will start in August 2026 The State of AI Governance in BFSI 2026. In the United States, companies that use AI for things like credit or checking for fraud must follow many federal rules AI Compliance for Financial Services — US State Laws & Frameworks. Even in the UK, while new AI-specific rules are not planned for 2026, existing rules are expected to cover AI uses UK Financial Services Regulators’ Approach to Artificial Intelligence in 2026. All these changes show that getting "credit ai" right is more important than ever.
This guide is for business leaders, investors, legal teams, and anyone else who needs to understand the tricky world of technology rules.
Maybe you’re a CEO planning for the "future of ai," or a compliance officer making sure your company avoids big fines. You might be an investor wanting to know the risks before putting money into new "ai problem solver" companies. If you’re using or thinking about using AI in your business, especially for credit, these rules affect you directly.
After reading this guide, you will be better able to understand the risks linked to AI in credit, know how to make compliance a top priority, and set up your business plans to match what regulators expect. This will help you skillfully handle the changing landscape of AI rules and ensure your company stays on the right side of the law. You’ll learn how to AI regulation 2026 navigate compliance and avoid risks effectively.
Staying updated is key to navigating these fast-moving changes.
The AI Newsletter Worth Reading
The rules for using AI to make credit decisions are quickly changing around the world. As businesses adopt more ai applications, understanding these rules is not just a good idea, it’s a must. Regulators are mostly focused on making sure AI is used fairly, that people can understand how decisions are made, and that companies manage risks well.
What’s Happening in Different Places
-
In Europe: The EU AI Act is a big deal. It calls systems that check someone’s credit score "high-risk." This means companies using these credit ai tools will need to have human oversight and keep good records for how their AI works. These important rules for high-risk AI are set to fully start in August 2026. This also covers things like how loans are approved and prices are set for insurance DORA, the EU AI Act, and Data Sovereignty. The European banking sector is carefully looking at how the AI Act impacts its operations AI Act: implications for the EU banking and payments sector.
-
In the United States: Here, the approach is a bit different. There aren’t special laws just for AI, but existing laws are being used to guide how AI is handled. For example, rules about treating everyone fairly when giving credit apply to AI just as they would to people making decisions. Banks, lenders, and fintech firms using AI for credit in 2026 must follow many federal laws and a growing number of state laws AI in Banking & Financial Services: State-by-State Regulation Guide …. Also, the U.S. Department of the Treasury recently shared new advice to improve cybersecurity and how risks are managed for AI in finance Treasury guidance brings urgency to AI governance. It’s also worth noting that some new guidance on managing model risks has specifically said that newer forms of AI, like generative AI, are not included in their scope Regulatory Compliance and Oversight.
-
In the United Kingdom: The UK is not planning to make new, specific AI laws for financial services in 2026. Instead, they expect companies to use current rules and ways of thinking when they build or use AI. This means rules about protecting customers and making sure top managers are responsible still apply to AI The AI Revolution Navigating the Regulatory Landscape in UK …. One important point for companies is to be clear with customers about services that use AI Financial Services AI Adoption Plan – GOV.UK.
Global Focus Areas
Around the world, there’s a push for "responsible AI." This means making sure ai problem solver tools are developed and used in a way that is fair, open, and keeps people safe. Regulators are increasingly looking at:
- Algorithmic Oversight: This is about understanding how AI makes decisions. It’s not enough to just get an answer; companies must be able to explain why the AI came up with that answer. This helps make sure decisions are fair and correct. You can learn more about this by exploring explainable AI for 2026 compliance and executive trust.
- Anti-Discrimination Rules: A big worry with AI is that it might accidentally treat groups of people unfairly. Regulators are working to prevent this and want companies to check their AI tools for bias. This helps ensure that the future of ai is fair for everyone.
- Risk Management: Companies need strong plans to find, measure, and deal with any risks that come from using AI, especially in sensitive areas like credit. This includes regular checks and updates to their AI systems.
The International Regulatory Strategy Group (IRSG) published a report in January 2026 that looked at how countries are approaching AI in financial services IRSG report on AI in financial services: emerging global norms. This shows a shared understanding across borders that AI needs careful handling.
Regulators worldwide agree that AI needs careful handling. But what does that really mean for businesses using credit ai to make decisions about loans or credit scores? It means focusing on "model risk management" and making sure these advanced tools are explainable.
Understanding Model Risk for Credit AI
Model risk is a big deal when it comes to using AI for credit decisions. It’s about the possible bad things that can happen if your AI models are not used right. Think about these key areas:
- Fairness: Does the AI treat everyone equally, or does it accidentally lean towards or against certain groups of people? Regulators want to make sure AI doesn’t lead to unfair treatment. An AI model audit can help check for bias in outputs and ensure fairness AI Model Audit: A Complete Guide for June 2026.
- Accuracy: Is the AI making correct predictions most of the time? If a credit ai model often gives wrong answers, it can hurt both the business and the customers.
- Robustness: Can the AI handle small changes in the data it sees without breaking down or giving wildly different answers? A strong model stays reliable even when things are not exactly perfect.
- Drift: AI models can sometimes "drift" over time. This means their performance gets worse as real-world data changes from the data they were first trained on. Keeping an eye on model quality helps detect this problem Step 4: Model Quality Monitoring.
Actually, new rules have changed how model risk is seen. For example, in April 2026, the US interagency guidance on model risk management was updated, and it specifically says that newer forms of ai applications like generative AI are not included in its scope AI in Lending Compliance: How to Pass a Regulatory Audit. This creates new challenges for those building the future of ai in finance.
Practical Steps for Managing AI Model Risk
To manage these risks and keep regulators happy, companies using credit AI should take several key actions:
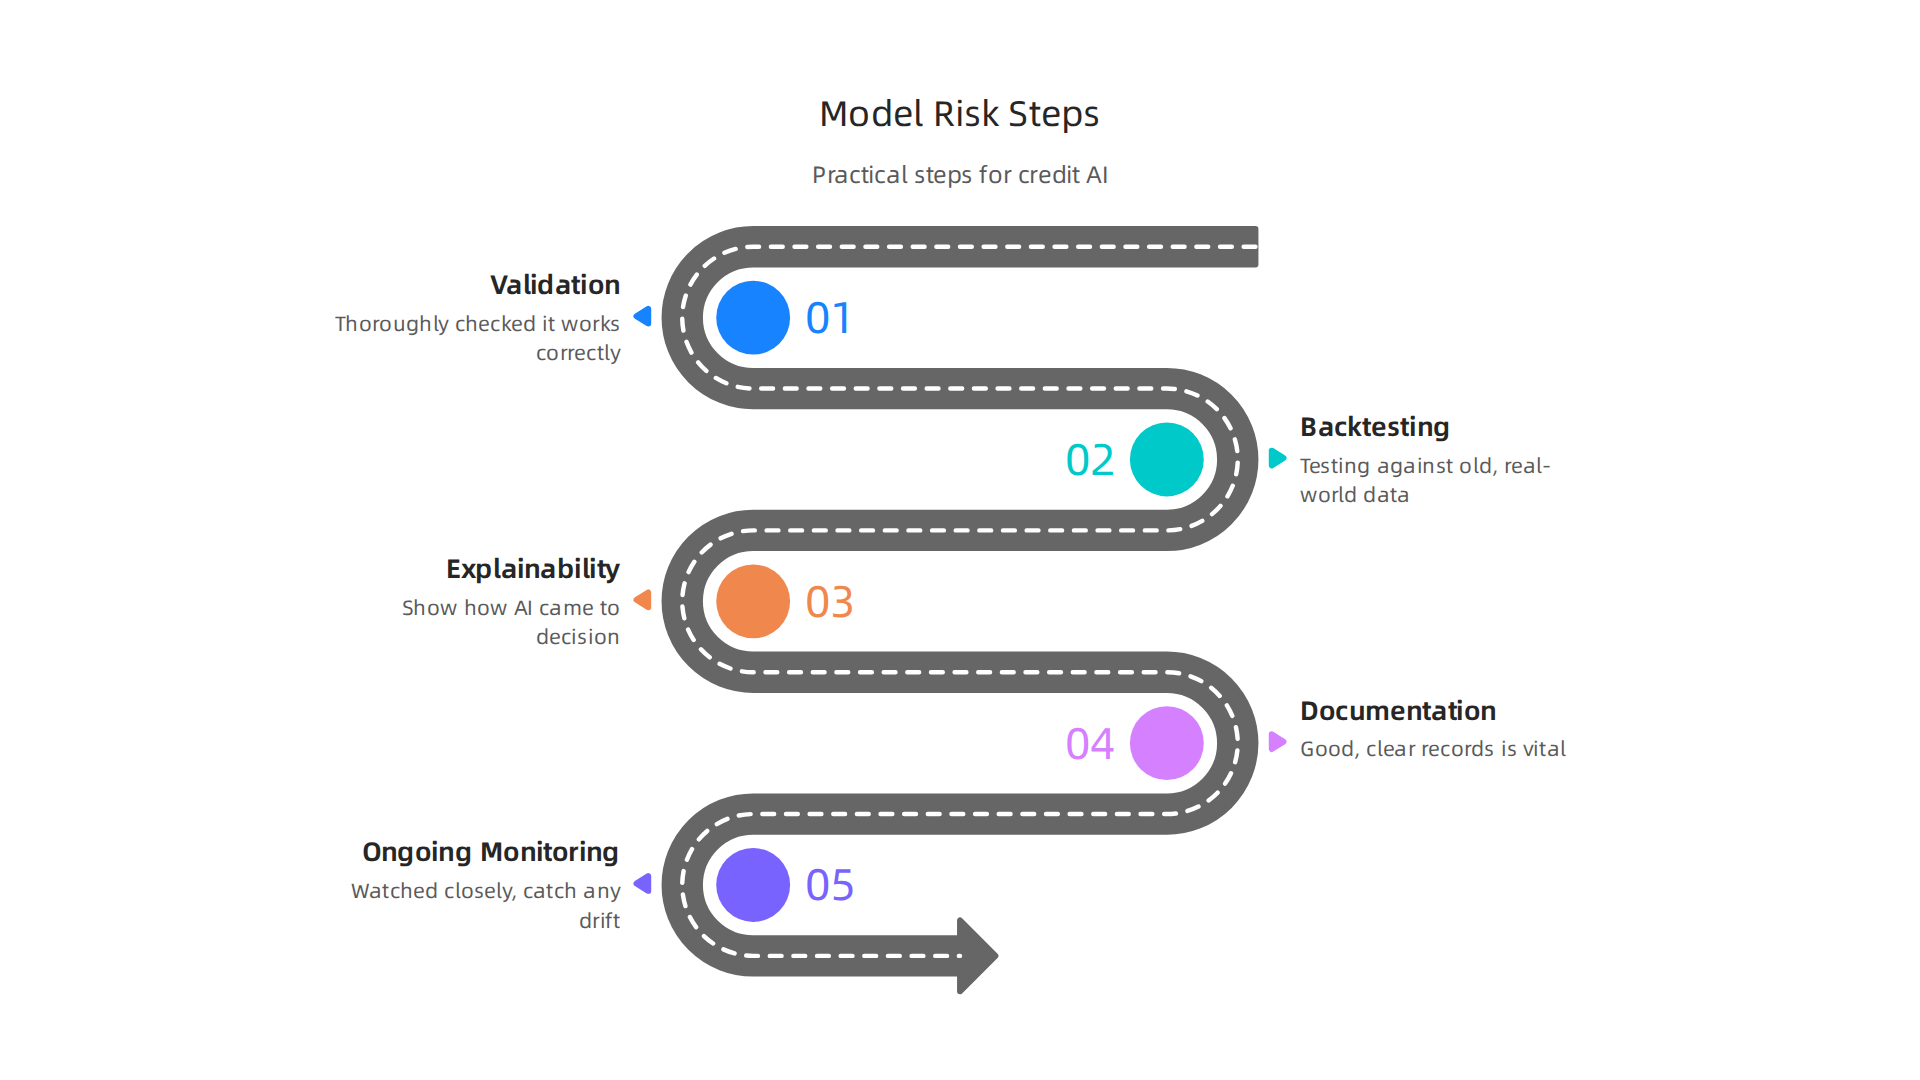
- Validation: Before an AI model is used, it must be thoroughly checked to confirm it works correctly and meets all expectations. This often involves an independent review Credit Risk Management Challenges: 2026 Guide for Lenders.
- Backtesting: This means testing the AI model against old, real-world data to see if its past predictions would have been right. It’s like checking its homework.
- Explainability Techniques: This is a very important part. Companies need to be able to show how the AI came to its decision. It’s not enough for an AI to just say "yes" or "no" to a loan application. People need to understand the reasons behind that answer. This is known as Explainable AI (XAI) and it’s changing how credit risk models are built How Explainable AI Is Reshaping Credit Risk Modelling. The goal is to provide clear, easy-to-understand reasons for every credit decision made by AI AI Model Explainability Requirements for US Banks: Adverse….
- Documentation for Exam Readiness: Keeping good, clear records is vital. This includes how the AI was built, how it was tested, how it’s being used, and any changes made to it. When regulators come to check, they will want to see all this paperwork.
- Ongoing Monitoring: Even after an AI is put into use, it needs to be watched closely. This continuous check helps catch any drift or changes in performance early on PD CEN ISO/TS 24971-2:2026.
Navigating all these rules and ensuring your AI models are compliant can feel like a lot. It’s crucial to stay informed about the latest regulatory changes and best practices.
Get clear daily AI updates from The Deep View Newsletter. The AI Newsletter Worth Reading
While managing model risk is crucial, another big part of the puzzle for credit AI involves the very information these systems learn from and use: data. This includes how data is gathered, protected, and kept in good shape.
Data Privacy, Consent, and Data Quality Issues for Credit AI
When we talk about using credit AI, we have to think a lot about data. This data is like the food for the AI; it needs good food to work well.
But there are important rules about this "food."
Privacy Laws and Consent
First, there are privacy laws. These rules are put in place to protect people’s private information. For example, in the US, new rules are always being set to help companies handle data carefully, including AI governance US Tech Regulations 2026: Navigating Data Privacy, AI Governance, and Antitrust Rules.
This means that for any credit AI to work, it must use data that people have agreed to share. This is called consent. You can’t just take someone’s financial history and feed it into an AI without their permission. Also, companies need to practice "data minimization." This big phrase just means using only the smallest amount of data needed for the AI to do its job. Don’t collect extra information that isn’t really necessary. These rules affect how AI models are trained and how they make credit decisions. They are especially important with technologies like biometrics and other advanced AI applications ID Tech Privacy Regulations in 2026 Force New Compliance Strategies for Biometrics and AI.
Data Quality and Bias
Next up is data quality. Think of it this way: if you put bad ingredients into a cake, you’ll get a bad cake. The same is true for AI. If the data used to train a credit AI is old, wrong, or incomplete, the AI will make bad decisions. This can lead to the AI being unfair to certain people or groups. This unfairness is called bias.
Here’s the thing: sometimes, historical data already has bias in it. For example, past lending choices might have accidentally favored some groups over others. If an AI learns from this biased history, it will repeat those unfair patterns in the future. Regulators know this is a problem. They expect companies to:
- Check Data Quality: Make sure the data is accurate, complete, and up-to-date. Tools are emerging to help businesses check for data quality, fairness, and bias in their AI systems Zensar Launches ZenseAI.AssureAI to Help Enterprises ….
- Look for Bias: Actively search for and fix any biases in the data before the AI uses it.
- Meet Expectations: Show regulators that they are trying their best to use fair and good quality data. This includes carefully looking at both the information that goes into the AI (inputs) and what the AI is trying to predict (labels).
Making sure data is private, collected with consent, and of high quality is not just a good idea; it’s a must-do for any business using credit AI today. It helps build trust and keeps companies in line with the rules.
Keeping companies in line with the rules for credit AI means more than just having good data. It also means showing how you follow those rules. This requires setting up smart ways to track, watch, and record everything your AI does. This process is called operationalizing compliance, and it involves audits, monitoring, and detailed paperwork.
Operationalizing Compliance: Audits, Monitoring, and Documentation
For businesses using credit AI, a big challenge in 2026 is proving to regulators that their AI systems are fair and work as they should. This means building clear audit trails, setting up ways to continuously watch the AI, and keeping good records.
Building Strong Audit Trails
Think of an audit trail as a complete diary of your AI’s life. It should record every important step. For credit AI, this means logging everything from how a model was approved to how it makes each decision AI governance, risk, and compliance in 2026. This diary needs to be detailed enough for someone else, like an auditor, to look back and understand exactly why the AI made a certain choice.
What should an audit trail include?
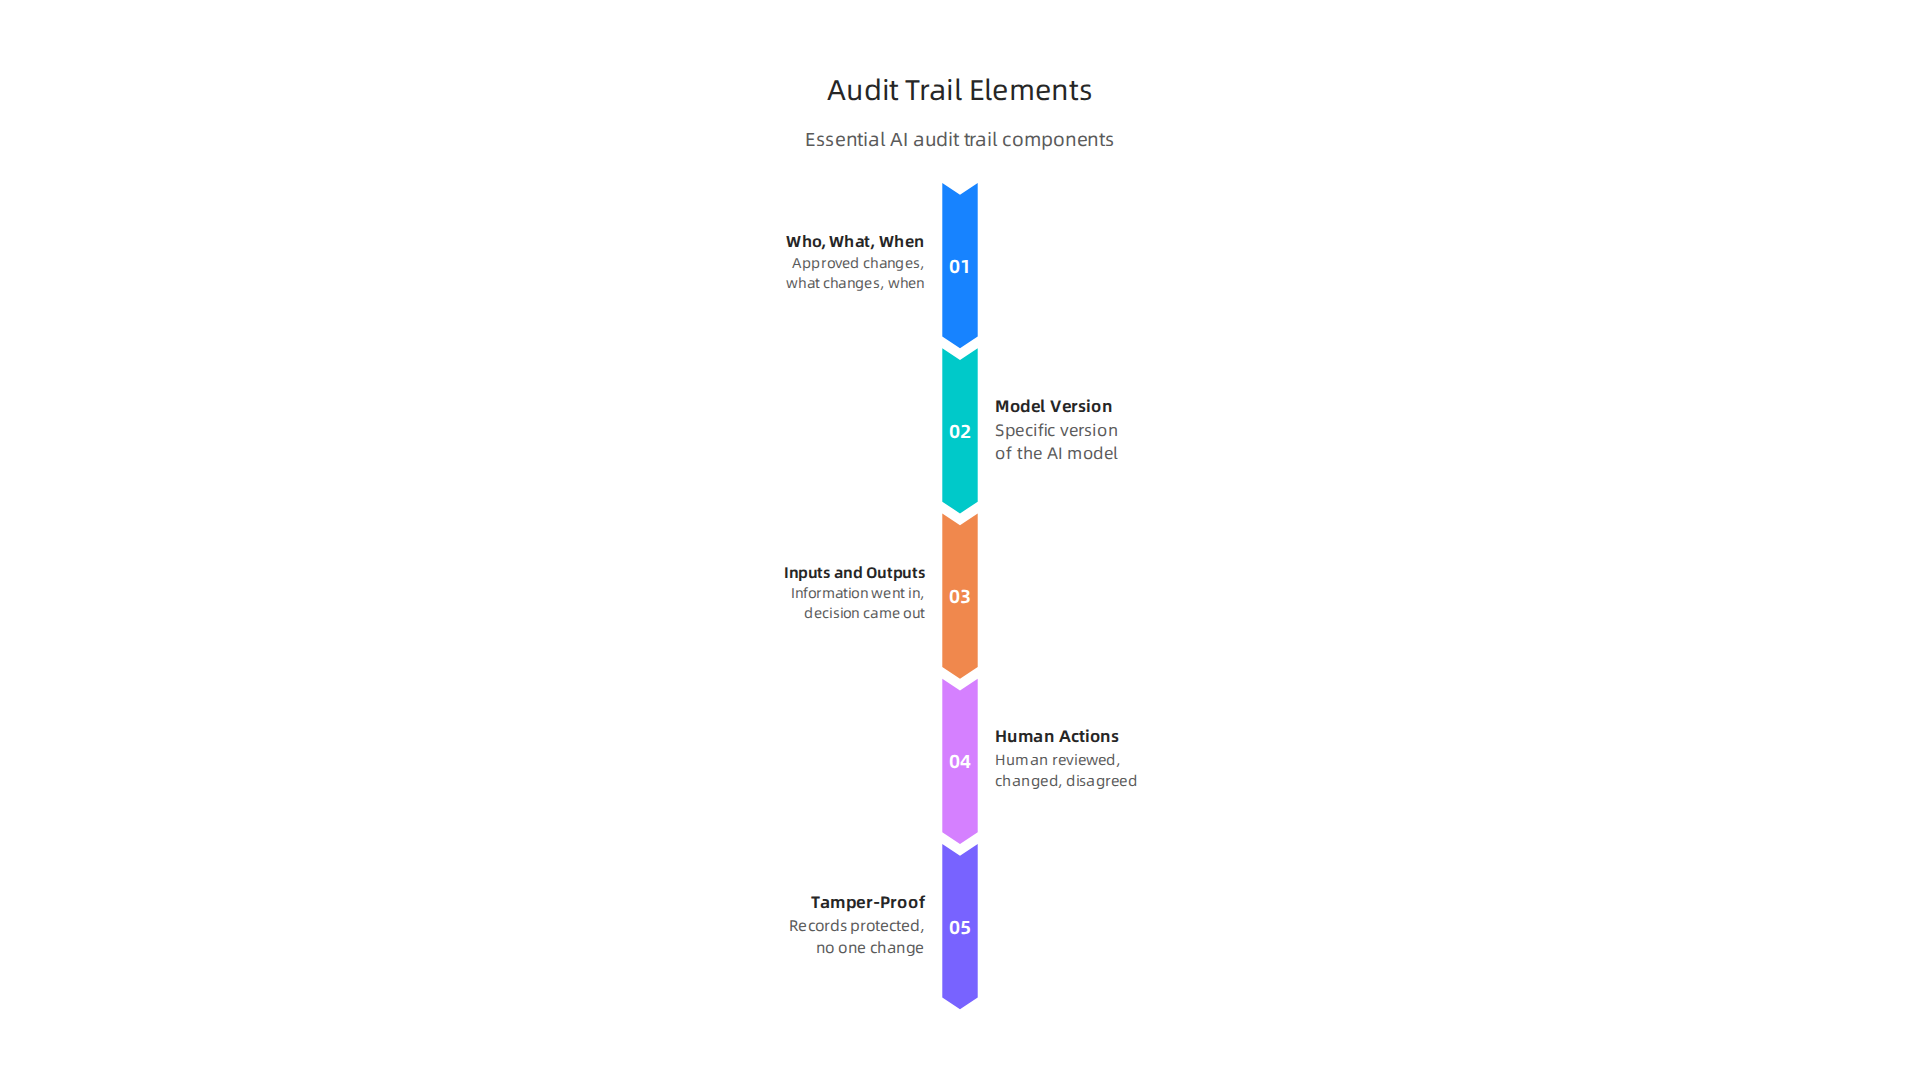
- Who, What, When: Who approved changes, what changes were made to the AI model or its data, and when these happened.
- Model Version: Which specific version of the AI model was used for a decision.
- Inputs and Outputs: What information went into the AI (the inputs) and what decision it came out with (the output), along with how confident the AI was in its decision.
- Human Actions: Any time a human reviewed, changed, or disagreed with an AI decision must be recorded.
- Tamper-Proof: The records should be protected so no one can secretly change them later. In 2026, a good audit trail captures at least 12 fields for every AI-influenced decision, including timestamps, unique decision IDs, and the AI system’s identity AI Audit Trail Requirements: A 2026 Checklist for Finance.
These detailed records help show that your credit AI applications are transparent and accountable.
Continuous Monitoring of AI Performance
It’s not enough to just build an AI and hope it works perfectly forever. AI models can change over time, or the data they see can change. This can make the AI less fair or less accurate. That’s why continuous monitoring is a must. This means constantly checking the AI system for:
- Performance: Is the AI still making good credit decisions?
- Drift: Has the AI’s behavior changed over time?
- Bias: Is the AI still fair to all groups of people, or has it developed new biases?
If monitoring shows a problem, like the AI starting to favor one group over another, you need to be able to catch it quickly and fix it. This proactive approach ensures your AI remains a fair and reliable ai problem solver.
Clear Documentation and Compliance Playbooks
Finally, everything needs to be written down. Good documentation is like a rulebook for your credit AI systems. It should clearly explain:
- How each AI model was built and tested.
- The rules it follows to make decisions.
- How your company handles new risks.
- Who is responsible for what (internal roles).
- What to do if something goes wrong.
This kind of paperwork should cover the whole life of the AI, from when it’s just an idea to when it’s actively making decisions and even after it’s retired. Regulators expect companies to have formal documentation that accurately reflects the AI’s architecture and processes AI Governance Documentation: Essential Audit Evidence Guide.
Some companies create "compliance playbooks." These are like step-by-step guides that help different teams, like legal, tech, and business teams, work together to meet all the rules. They map out data paths, assign ownership, and automate key steps for showing compliance The AI Compliance Playbook for Banks and Lenders 2026. Having these playbooks ready makes it much easier to collect evidence and report to auditors or regulators when needed. This helps integrate regulatory compliance into your corporate AI strategy. For more on making your AI understandable and trustworthy, read about Explainable AI for 2026 compliance and executive trust.
By setting up these audit trails, monitoring systems, and clear documentation, businesses can confidently manage their credit AI, stay compliant, and build trust in the future of ai.
Ready to stay updated on the fast-changing world of AI and regulation? Get clear daily AI updates. You can find out more with The AI Newsletter Worth Reading.
After setting up strong audit trails, continuous monitoring, and detailed documentation, the next big step for businesses using credit AI is to put clear governance in place. This means deciding who is in charge, making sure reviews are fair, and telling customers exactly how AI affects them. It’s all about making sure your AI systems are not just working well, but also working fairly and openly.
Governance, accountability, and consumer redress in credit AI
In 2026, companies using credit AI must focus on three main areas: clear governance, strong accountability, and ways for consumers to fix problems. These steps help build trust and ensure that everyone is treated fairly.
Setting Up Clear Governance Structures
Governance is about who makes the rules and who is responsible for following them. For credit AI, this means having:
- Senior Accountability: Leaders at the top must take responsibility for how AI systems are designed and used.
They need to make sure the AI is fair, unbiased, and compliant with all regulations. This includes understanding the risks and guiding the company’s overall strategy for AI governance in financial services.
- Independent Review: It’s a good idea to have different teams or outside experts check the AI systems. This independent review helps catch problems that internal teams might miss. It adds another layer of trust and makes sure the AI isn’t showing bias or making bad decisions. This kind of oversight is key for regulated AI model governance in 2026.
- Consumer-Facing Disclosures: Companies should be open with their customers. This means clearly explaining when and how credit AI is used to make decisions. Transparency builds trust. People need to know their rights and how to question a decision made by an AI. This is a vital part of integrating regulatory compliance into your corporate AI strategy.
Ensuring Accountability and Consumer Rights
What happens when a credit AI makes a decision that someone thinks is wrong? Companies need clear ways to handle these situations.
- Adverse Action Notices: If a person is denied credit, or if their credit terms are made worse because of an AI decision, they need to know why. These "adverse action notices" should be clear and explain the main reasons for the decision. This helps people understand what happened and gives them a chance to fix any issues. Companies need to have systems in place to make sure these notices are accurate and timely.
- Dispute Resolution: People should have an easy way to challenge a credit AI decision they believe is unfair. This means having a clear process for disputes. Someone from the company, likely a human, should review the AI’s decision and the information provided by the customer. This ensures that the customer’s side of the story is heard and that mistakes can be corrected.
- Remediation Frameworks: If it turns out that a credit AI made a wrong decision, especially one that hurt a customer, the company must fix it. A remediation framework outlines how to make things right. This could mean changing a credit score, re-evaluating an application, or even offering compensation. Having these steps ready shows that the company takes its responsibility seriously and wants to be a fair AI problem solver for all customers.
By putting these structures and processes in place, businesses can make sure their credit AI applications not only follow the rules but also serve customers ethically and effectively, paving the way for a more responsible future of ai.
When companies use credit AI across different countries, things get much more complex than just operating in one place. What works in one nation might break laws in another. In 2026, businesses must carefully think about these international differences to avoid big problems and make sure their AI systems are fair everywhere.
Key Challenges for Global Credit AI
Deploying credit AI in many countries creates a few friction points that companies need to understand:
- Data Transfer Rules: Every country has its own rules about how personal data can be collected, stored, and moved across borders. For example, the European Union has strict GDPR rules that say data can only be sent to countries with similar strong protections, or if special agreements are in place. This can make it hard to use one central AI system for all global credit applications, because data might need to stay within certain borders.
- Different Fairness Standards: What is considered "fair" for a credit decision can change from one country to another. Some places might focus on preventing bias against certain groups based on age or gender. Other places might have different ideas about what is acceptable. This means an AI system that is fair in one region might accidentally show bias somewhere else. Countries around the world, including the EU, the UK, the US, and Singapore, have different ways of looking at AI rules in finance, including how they govern algorithmic credit scoring systems for fairness and transparency 1. The EU AI Act, for instance, marks AI systems used for creditworthiness checks as "high-risk," requiring careful oversight 2.
- Rules for Third-Party Vendors: Many companies don’t build all their AI systems themselves. Instead, they use outside vendors or partners. When operating across borders, companies need to make sure these third-party vendors also follow all the local rules for AI governance in financial services. This adds another layer of checking and compliance to an already tricky situation.
Harmonizing Controls and Staying Compliant
To manage these challenges, businesses need smart strategies to keep their AI applications compliant and ethical across different markets.
- Set the Highest Standard: A good approach is to build credit AI systems that meet the strictest regulations found in any country where the company operates. If your AI is designed to meet the EU AI Act’s high-risk obligations, which went into full effect on August 2, 2026, it will likely cover many requirements in other regions too 3. This "highest common denominator" method helps reduce the risk of non-compliance.
- Local Adjustments and Expertise: Even with a high global standard, some local fine-tuning will be needed. Companies should work with local legal experts and AI specialists in each market to understand specific rules and cultural ideas of fairness. This helps adapt the credit AI to local needs without breaking the core global framework.
- Clear Data Policies: Businesses need clear policies for how data is handled. This means knowing exactly where data comes from, where it is stored, and who can access it. Using tools like data anonymization or local data processing can help manage cross-border data transfer rules. The GDPR, for example, has rules about sending personal data outside the EU, allowing it only if the receiving country has similar strong protections or if other safeguards are in place 4.
- Continuous Monitoring and Updates: Regulatory landscapes for AI are always changing. Companies must continuously monitor new laws and update their credit AI systems and policies. Regular audits and reviews, both internal and external, are essential for staying compliant with different national requirements. This makes sure that your AI systems are not just working well today, but will also work well in the future of AI.
By taking these steps, companies can make sure their credit AI systems are effective and trusted, no matter where in the world they are used.
Want to stay informed on the fast-changing world of AI and technology regulations? Get daily updates. The AI Newsletter Worth Reading.
Making sure your credit AI systems work well and are trusted everywhere in the world also changes how businesses plan for the future and how investors make choices. This involves looking closely at risks, the money spent on following rules, and new chances that pop up.
Business and investment implications: risk, compliance costs, and strategic opportunities
The rules about AI, especially for credit AI, are a big deal for companies and investors in 2026. These rules affect everything from what new products companies build to how they grow and even if they decide to buy other companies.
How Rules Change What Products Are Made and Sold
For companies that make or use credit AI, new laws mean they have to be very careful about their product plans. The EU AI Act, for example, says that AI systems used for checking a person’s credit are "high-risk." This means they need a lot of extra checks and balances 1. If an AI application is called "high-risk," it needs strong risk management, tests for unfairness, human oversight, and clear paperwork 2.
This means companies might spend more money and time to make sure their AI products follow all the rules before they can sell them. Regulators are looking closely at how AI makes credit decisions, how it explains denials, and if it’s fair 3. This can slow down getting new AI tools to market.
What Regulations Mean for Buying and Selling Companies
For investors and companies looking to buy other firms, understanding AI regulations is key. If a company they want to buy uses credit AI, they need to know if that AI follows all the rules. The US, for instance, has several federal rules that banks, lenders, and fintechs must follow when using AI for credit decisions 4. Checking this takes time and can affect how much a company is worth. Investors also need to think about future rules. A company that is good at planning for future AI laws will be more attractive.
A Way to Check AI Rules for Investors and Executives
To help assess risks and readiness, investors and business leaders can use a simple way to look at things:
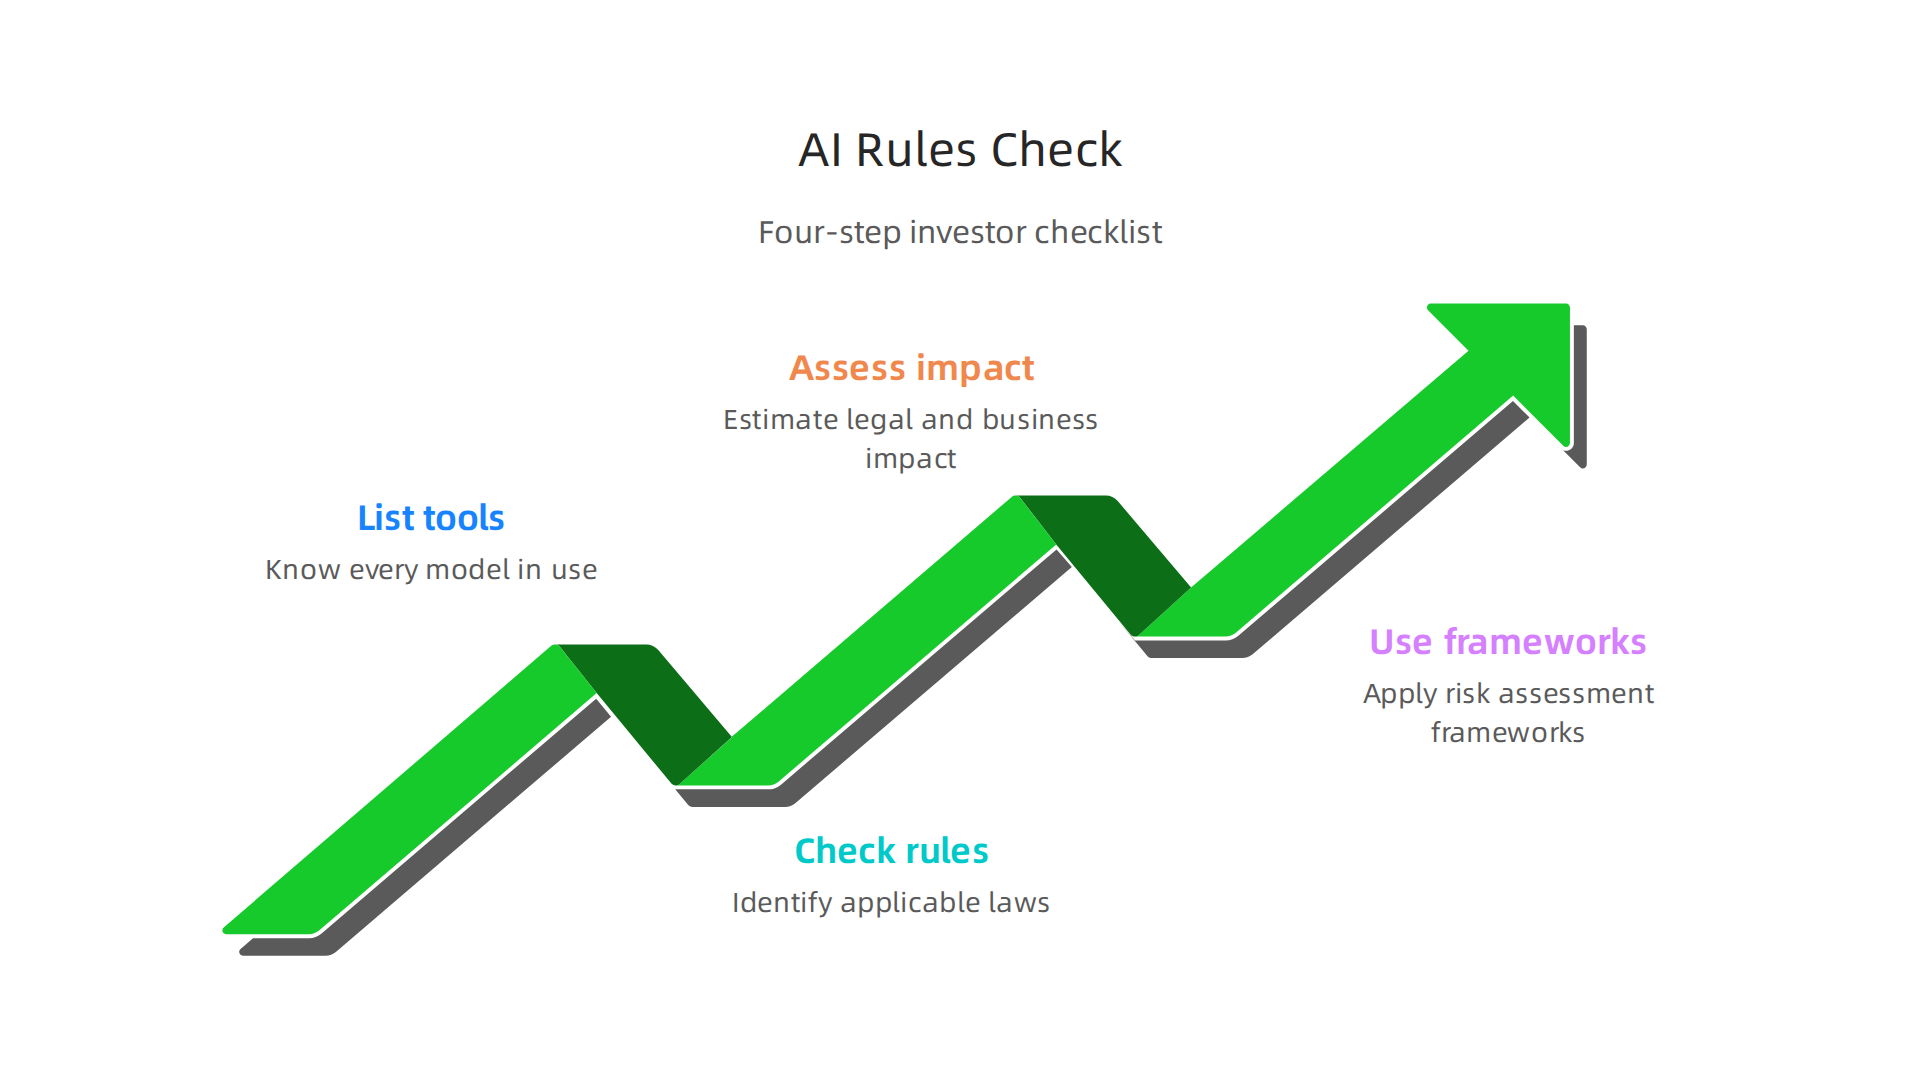
- List all AI tools: Know every AI model your company uses, especially those from outside vendors. Write down what decisions each AI helps with, what data it uses, and who is in charge of it 5.
- Check the rules: For each AI, find out which laws apply to it. For example, the Colorado AI Act (CAIA) requires special reports and risk plans for high-risk AI systems in finance, lending, and credit 6.
- See the impact: Think about what could happen if an AI breaks a rule. Could there be big fines? Damage to the company’s name?
- Use frameworks: Companies like Wolters Kluwer offer tools to evaluate AI risks, looking at how much risk there is, how many rules apply, and how bad the impact could be if something goes wrong 7. The US Treasury also has guidance on an AI Risk Management Framework to help 8.
These checks help leaders understand how ready their company is for the changing world of AI rules. For more guidance on managing complex tech rules, consider learning how to mastering AI capabilities.
Finding New Chances in Compliance
While rules can seem like a problem, they also bring chances. Companies that do a great job of making their credit AI fair, safe, and transparent can stand out. Being a leader in AI compliance can build trust with customers and regulators, which can lead to more business and a better name in the market. Investing in good AI governance now can help companies avoid bigger problems later and become a trusted ai problem solver for customers and other businesses.
Summary
This guide explains why regulating AI used for credit decisions matters now and walks business leaders, compliance teams, and investors through what they must do to stay compliant in 2026. It covers the shifting global landscape — from the EU AI Act’s high‑risk rules to US federal and state approaches and the UK’s reliance on existing frameworks — and identifies the model risks regulators focus on: fairness, accuracy, robustness, and drift. You will learn practical steps such as validation, backtesting, explainability techniques, and continuous monitoring, plus how to document audit trails and operationalize compliance. The guide also covers data privacy and consent, strategies for cross‑border deployment, governance and consumer redress, and the business and investment implications of stronger AI rules. After reading, you will be able to prioritize model risk controls, set up audit-ready processes, and adapt product and M&A plans to evolving AI regulation.